Using Your Home Equity to Downsize in Long Beach
Using Your Home Equity to Downsize in Long Beach can turn years of ownership into a more manageable next step when sale proceeds, replacement housing costs, and timing are considered together. For many longtime owners, a downsize can reduce maintenance, lower monthly obligations, or create more flexibility for retirement goals. Marie Goodloe helps homeowners evaluate what they may keep after a sale, what a smaller home may cost, and how to plan a move without rushing the financial decisions.
Home Equity & Downsizing: Long Beach at a Glance - Using Your Home Equity to Downsize in Long Beach
Long Beach homeowners should begin with a local household and housing snapshot, then build a property-specific net-proceeds plan. The following figures describe the Long Beach postal-city area and offer context rather than a prediction of any individual home's value (Long Beach, CA):
- Median home value: $899,317.
- Owner-occupied households: 41.02% of households.
- Median household income: $80,394 per year.
- Median year homes were built: 1965.
Your usable equity will depend on your actual sale price, remaining mortgage balance, transaction costs, and replacement-housing choice.
How Much Equity Do Long Beach Homeowners Typically Hold? - Using Your Home Equity to Downsize in Long Beach
Long Beach homeowners typically hold meaningful equity when their probable sale price exceeds their mortgage payoff and selling expenses. The exact amount can vary substantially, even between nearby homes, because purchase date, loan terms, improvements, property condition, and market appeal all affect the final result.
Equity generally grows through appreciation and principal repayment. Owners who have stayed in one home for many years may have reduced their loan balance while building value in a property that no longer fits their space, mobility, or maintenance preferences. That can make downsizing especially relevant for retirees, empty-nesters, and sellers who want to convert home value into greater flexibility.
The local housing context also matters. A median home value of $899,317 in the Long Beach postal-city area suggests that substantial value may be tied up in a primary residence, but gross value is not the same as available cash. A mortgage payoff, seller-side costs, moving expenses, and the cost of the next home all reduce the funds left after closing.
A useful downsizing estimate starts with four figures: likely sale price, loan payoff, selling costs, and replacement-housing cost. Reviewing those figures together is more reliable than focusing on a headline home value alone.
Turning Equity Into a Downsizing Plan: The Core Options
Long Beach homeowners generally have three paths for using equity during a downsize: sell and buy a smaller home, sell and rent, or use temporary home-equity financing while coordinating a move.
Sell and buy a smaller home. This approach can suit owners who want a permanent move and more predictable housing costs. Net proceeds may support a smaller mortgage or an all-cash purchase, depending on the home's sale price and the replacement property's cost. It can be a practical fit for retirees who want fewer maintenance responsibilities and a clearer monthly budget.
Sell and rent. Selling before renting can provide flexibility for households that want time to compare buildings, neighborhoods, and lifestyle needs without making another purchase immediately. This option can work well when a homeowner wants liquidity or is uncertain about a long-term location. The tradeoff is that rent remains an ongoing expense, so proceeds should be planned around reserves, investments, and future housing needs.
Use a HELOC or reverse mortgage as a bridge. A home equity line of credit may help cover a short transition before a sale closes, while a reverse mortgage may be relevant for qualifying older owners. Both options require careful review of repayment terms, fees, occupancy rules, taxes, insurance, and timing. They are financing tools, not automatic solutions, and should be evaluated with qualified lending and financial professionals.
Know Before You Sell: Equity Tap vs. Outright Sale
- Cash-flow risk: Do not treat borrowed funds as final sale proceeds before closing. Delays, repairs, or pricing changes can affect the amount available.
- Capital gains: Eligible primary-residence sellers may exclude up to $250,000 of gain, or up to $500,000 for many married couples filing jointly, subject to IRS requirements (IRS Publication 523).
- Overlap costs: Carrying both the current home and replacement housing can mean duplicate mortgage, insurance, utility, and association expenses.
- Bridge-financing tip: Compare fees, repayment obligations, and the expected sale timeline before using temporary borrowing to support a purchase.
Downsizing Scenarios: What the Numbers Can Look Like in Long Beach
The financial outcome of a Long Beach downsize depends on a home's actual sale price, mortgage payoff, condition, replacement housing, HOA obligations, and moving timeline. Rather than relying on generalized figures, homeowners should request a tailored estimate for each of these common paths:
- Selling a family home and purchasing a two-bedroom condo may reduce exterior maintenance, although HOA dues, insurance responsibilities, and potential special assessments should be included in the monthly comparison.
- Selling a family home and moving to a 55+ community can offer a more age-focused lifestyle, but buyers should review ownership rules, community fees, resale restrictions, and the services included.
- Selling a family home and renting a two-bedroom apartment may preserve more immediate liquidity, but first-year rent, a security deposit, renter's insurance, and future rent changes remain part of the plan.
A personalized net-proceeds estimate can show whether a particular path frees cash, reduces monthly costs, or simply exchanges one set of expenses for another.
The True Cost of Downsizing in Long Beach
Downsizing in Long Beach costs more than the difference between two home prices. A complete plan includes the expenses of selling, moving, and making the replacement home functional for daily life.
Start with the sale. Sellers should review the compensation and services outlined in their listing agreement, along with title, escrow, recording, negotiated credits, and any property-preparation expenses. The final allocation of costs depends on the purchase contract and transaction terms, so a written net sheet is valuable before committing to a replacement home.
Moving costs can also be meaningful for longtime owners. Packing, movers, storage, utility transfers, cleaning, disposal, and furniture changes can add up quickly. A smaller residence may also need paint, flooring, accessibility updates, window coverings, or storage solutions before it feels move-in ready.
For condominiums and planned communities, monthly HOA dues are only part of the equation. Buyers should examine reserves, insurance responsibilities, special-assessment history, parking, pet rules, rental limitations, and maintenance obligations. A lower purchase price does not automatically create a lower monthly housing cost.
One common surprise is preparing two homes at once: making the current property market-ready while improving the replacement home before moving in. A contingency reserve can make that overlap less stressful.
Tax Considerations Every Long Beach Downsizer Should Understand
Long Beach sellers may qualify for a federal primary-residence gain exclusion when they meet applicable ownership and use requirements. In many cases, an eligible individual can exclude up to $250,000 of gain, while certain married couples filing jointly may exclude up to $500,000.
California treatment deserves separate attention. California generally does not apply a preferential state tax rate to capital gains; taxable gains are typically included in California taxable income. A homeowner's adjusted basis, qualifying improvements, ownership history, and previous exclusions can all affect the calculation. The California Franchise Tax Board provides state guidance on capital gains and losses.
For qualifying homeowners age 55 or older, California Proposition 19 may allow a homeowner to transfer a factored base-year value from a primary residence to a replacement primary residence anywhere in California, subject to eligibility, filing, and timing requirements. The California State Board of Equalization explains the program and its rules.
Tax results depend on individual circumstances, including ownership period, prior use, improvements, and sale timing. Homeowners should speak with a qualified tax professional and the appropriate county assessor before finalizing a sale or replacement-home purchase.
Pro-Tip: For eligible homeowners age 55 or older, Proposition 19 may help preserve a lower assessed-value base after a move, which can be as important as the cash released at closing.
Where Downsizers Are Landing in Long Beach
Long Beach downsizers often look for homes that reduce maintenance while keeping familiar amenities, transportation options, and everyday services nearby. The right fit depends on budget, mobility needs, parking preferences, and comfort with HOA governance.
For homeowners looking to simplify their next chapter, single-level homes and lower-maintenance properties can be worth exploring. Ground-floor condos, smaller detached homes, and patio-style residences offer different levels of privacy, accessibility, and exterior upkeep. Before choosing where to move, explore our guide to finding a more manageable home in Long Beach to compare layouts, HOA responsibilities, and long-term ownership costs.
Belmont Shore and Naples can appeal to owners who value coastal access, walkable amenities, and condominium-style living. Buyers should compare HOA dues with the services included, such as exterior maintenance, common-area care, and insurance components.
Downtown Long Beach offers condominium and apartment-style housing near waterfront destinations, transit, restaurants, and cultural venues. Building financials, parking arrangements, elevator access, HOA rules, and reserve funding can be particularly important for buyers seeking lower-maintenance living.
Bixby Knolls may suit downsizers who prefer an established residential setting with neighborhood shops and a community-oriented feel. Smaller detached homes, attached residences, and nearby condominium options can create different tradeoffs between privacy and upkeep.
East Long Beach provides a mix of condos, townhomes, and smaller detached homes for owners who want to remain in Long Beach while exploring a more manageable property type. A comparison of HOA obligations, parking, and maintenance needs can be more useful than focusing on square footage alone.
How to Time Your Downsize in Long Beach
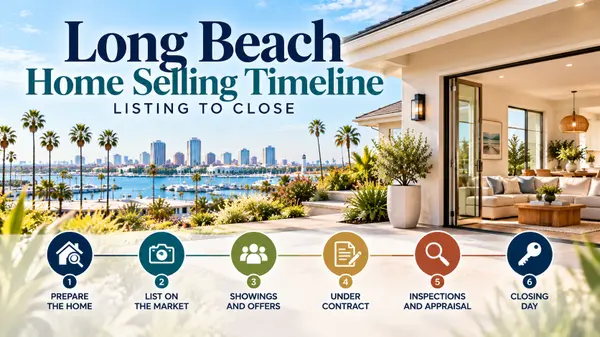
A successful Long Beach downsize begins with coordinating the sale and the next housing decision before either transaction becomes urgent. Smaller homes and condos can appear throughout the year, so homeowners benefit from monitoring suitable options early through an MLS listing search while preparing their current property for sale.
The central timing decision is whether to sell first or buy first. Selling first provides a clearer picture of available proceeds and can reduce the risk of carrying two properties for an extended period. Buying first may be appropriate when a specific replacement home is an unusually strong fit, but it requires a realistic plan for financing and overlapping costs.
A practical sequence is to estimate likely net proceeds, prepare the current home, and identify acceptable replacement options before listing. Sellers who need more time after closing can consider negotiating a leaseback arrangement. Buyers who need to secure a replacement home first should ensure that their contingency and financing terms reflect their actual ability to carry overlapping obligations.
Ready to Put Your Long Beach Equity to Work? - Using Your Home Equity to Downsize in Long Beach
Downsizing starts with understanding your home's value, expected sale proceeds, and the cost of your next property. Marie Goodloe of Y Realty helps Long Beach homeowners evaluate their options, compare lower-maintenance homes, and plan a move that fits their lifestyle and financial goals.
Whether you're preparing to sell or exploring a smaller home, contact Marie Goodloe or call (310) 251-0795 to discuss your next steps.
Frequently Asked Questions
How much equity do I need to make downsizing worth it in Long Beach?
There is no universal equity threshold that makes downsizing worthwhile. A downsize may make sense when the funds remaining after your mortgage payoff, sale expenses, moving costs, and replacement-housing costs improve cash flow or support a personal financial goal.
Will I owe capital-gains tax when I sell my home in Long Beach?
Not every seller owes federal tax on a home-sale gain. Homeowners who meet the applicable primary-residence rules may be able to exclude up to $250,000 of gain, or up to $500,000 for some married couples filing jointly, while California taxable gain is generally included in state taxable income.
What are the best neighborhoods or communities for downsizers in Long Beach?
Belmont Shore, Naples, Downtown Long Beach, Bixby Knolls, and East Long Beach each offer different paths to lower-maintenance living. The best match depends on whether you prioritize walkability, condo living, parking, association-managed upkeep, or a smaller detached home.
Should I sell first or buy first when downsizing in Long Beach?
Selling first can clarify the funds available for your next home and limit the period in which you carry two housing obligations. Buying first can work when a replacement home is a strong match, provided your financing, contingency terms, and backup plan are realistic.
Are there programs in Long Beach that help seniors with property taxes after downsizing?
Eligible California homeowners age 55 or older may be able to use Proposition 19 to transfer a factored base-year value to a replacement primary residence. The program has eligibility rules, deadlines, and filing requirements, so confirm the details with the county assessor and a qualified tax professional.
Categories
Recent Posts

GET MORE INFORMATION